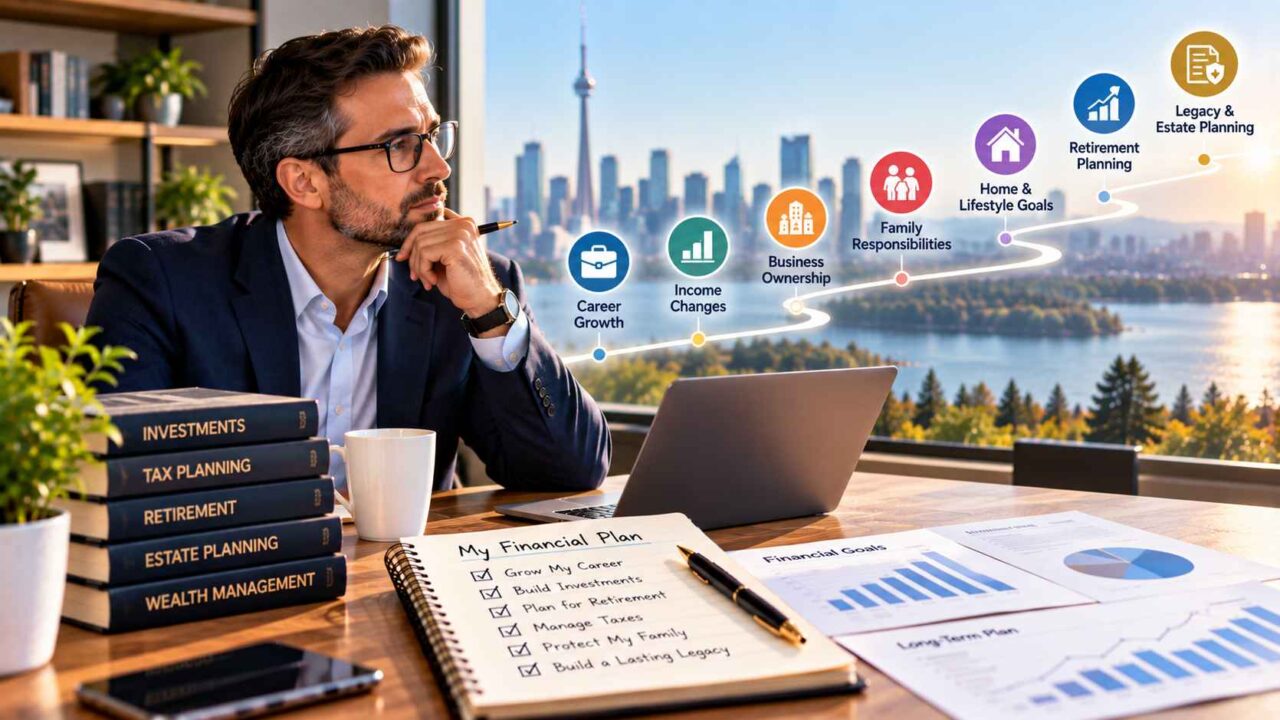

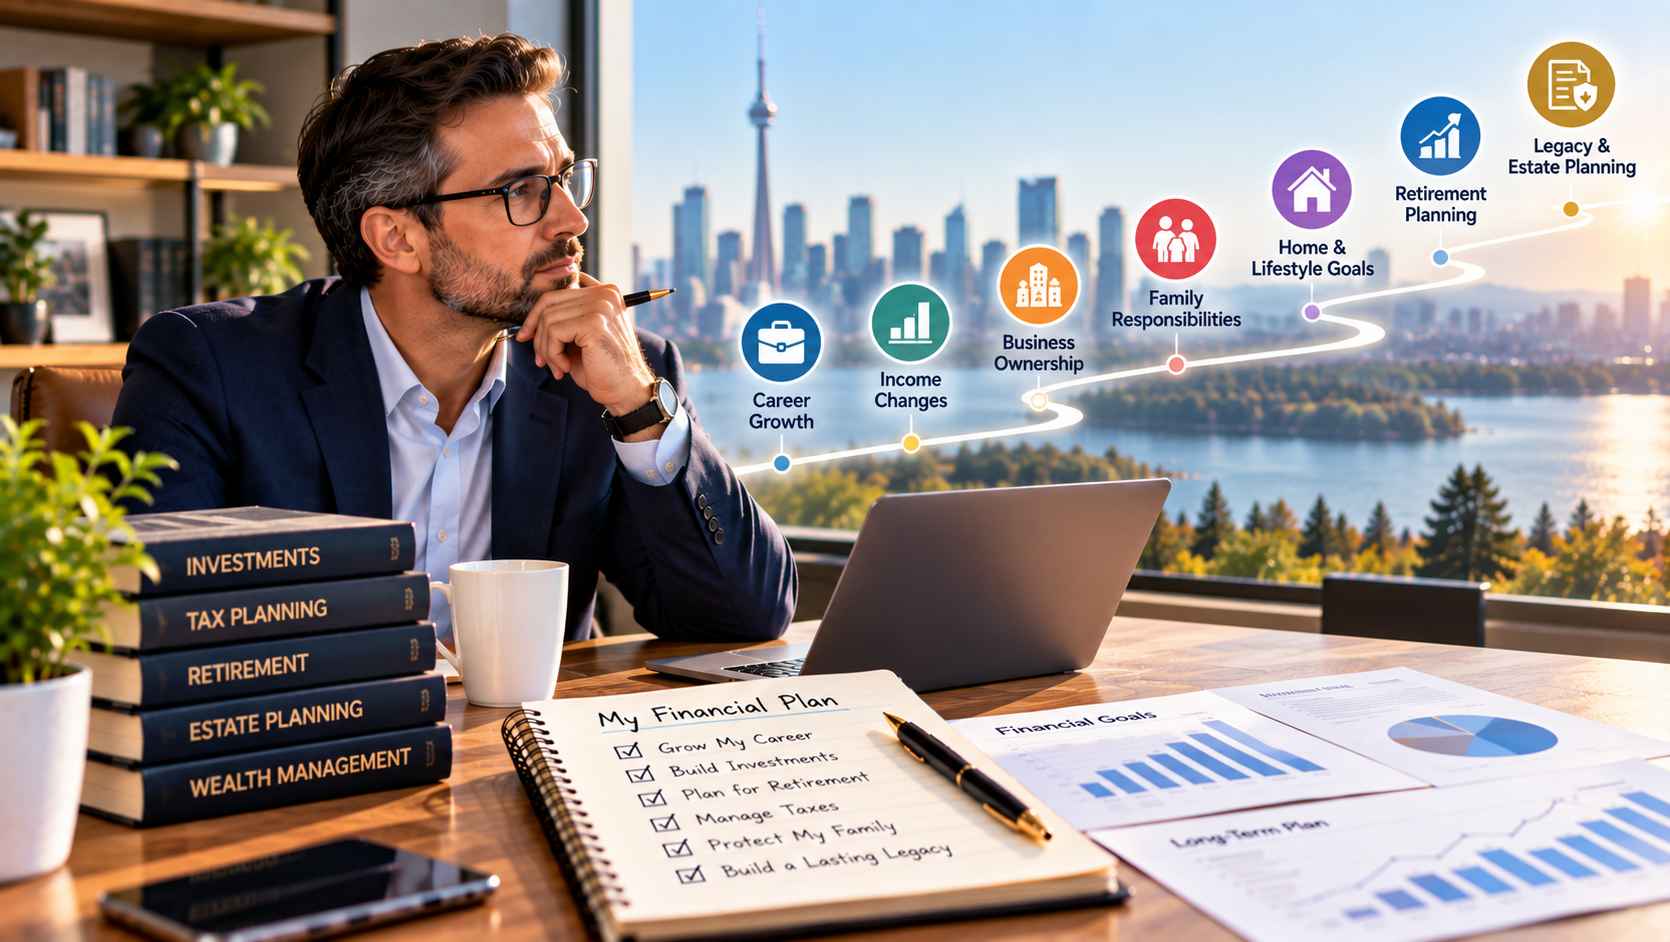
A financial plan can look very different at different stages of life. Early in a career, the focus may be on building savings and managing debt. Later, priorities can shift toward investment growth, business ownership, family responsibilities, retirement, or leaving a financial legacy.
The challenge is that these changes rarely happen one at a time. A new job can change income. Starting a business can change cash flow and tax considerations. Having children can alter insurance and estate-planning priorities. Approaching retirement can shift the focus from accumulation to income and preservation.
For that reason, financial planning is better viewed as an ongoing process than a document that is created once and left untouched.
Financial Planning Is Not a One-Time Exercise
A financial plan is meant to connect where someone is today with where they want to be in the future. That means it needs to reflect changing circumstances.
The Financial Consumer Agency of Canada describes a financial plan as a long-term roadmap that considers goals, resources, debts, taxes, insurance, pensions, and other factors, and notes that it should be kept up to date as a person’s situation changes. Financial planning guidance from the Government of Canada
This is particularly relevant for professionals whose careers or financial responsibilities evolve quickly.
Someone may begin with a straightforward employment income and gradually move into management, partnership, consulting, or business ownership. Their financial plan may need to change along with that progression.
A plan that was appropriate five or ten years ago may no longer reflect current priorities.
For professionals looking for a coordinated approach, Exponent Investment Management provides financial planning and wealth management services that can be considered alongside broader long-term financial objectives.
Career and Income Changes
Income is one of the biggest factors that can affect a financial plan.
A promotion may create additional savings capacity. A career change could temporarily reduce income. Self-employment or business ownership may create more variable cash flow. Bonuses, commissions, professional partnerships, or other compensation structures can also make annual income less predictable.
When income changes, it is useful to reconsider how the additional resources—or temporary reduction—affects other priorities.
For example, an increase in earnings could influence retirement savings, investment contributions, debt repayment, or cash reserves. A period of lower income might require a greater emphasis on liquidity and short-term flexibility.
Professionals should also consider whether their financial plan is overly dependent on continued income at its current level.
Career changes are not always negative events. They can create opportunities to pursue different work, start a business, reduce working hours, or change professional direction. A flexible financial plan can help accommodate those possibilities without treating the future as fixed.
Changing Investment Priorities
Investment goals can also change over time.
Someone in their early career may have a long horizon and focus heavily on building assets. Later, the same person may place greater importance on preserving wealth, generating income, funding education, purchasing property, or preparing for retirement.
The appropriate approach depends on individual circumstances, objectives, time horizons, and tolerance for investment risk.
The important planning principle is to review whether existing investments still serve the purpose they were originally intended to support.
Major life changes can be useful occasions for that review. A new business, a large inheritance, a property purchase, a change in family circumstances, or a significant change in income may alter how someone views liquidity, diversification, and long-term investment objectives.
Rather than making investment decisions in isolation, professionals can consider how their portfolio fits within their entire financial picture.
Retirement and Lifestyle Planning
Retirement planning is another area where assumptions can change.
A person may initially expect to retire at a particular age but later decide to work longer, transition gradually, pursue consulting work, or retire earlier. Lifestyle expectations can also evolve.
Retirement spending is not necessarily a simple continuation of current spending. Housing, travel, hobbies, family support, healthcare, and other priorities can change over time.
The Government of Canada’s retirement-planning resources emphasize considering factors such as retirement age, lifestyle, family responsibilities, debt, and expected sources of retirement income when determining retirement needs.
For professionals, the picture may include workplace pensions, registered savings, personal investments, business interests, government benefits, and other assets.
Reviewing these sources together can provide a clearer understanding of how retirement might be funded under different circumstances.
Tax and Estate Considerations
Tax planning can become increasingly important as income, investments, and assets become more complex.
A professional may move from employment income to a combination of salary, business income, investment income, or other sources. Each change can introduce different planning considerations.
Tax planning should not be treated as an isolated exercise. It can affect decisions involving investments, retirement income, business ownership, charitable giving, and estate planning.
Estate planning is similarly connected to the broader financial picture.
Professionals with significant assets or business interests may need to consider how those assets should be handled in the future, who should receive them, and how decisions should be managed if circumstances change unexpectedly.
Legal and tax requirements vary depending on individual circumstances and jurisdiction, so appropriate legal and tax professionals may need to be involved.
The role of broader financial planning is to help ensure these areas are considered together rather than addressed independently.
When to Review a Financial Plan
There is no single schedule that works for everyone, but certain events should prompt a closer look at the existing plan.
These can include:
- Starting or selling a business
- Changing careers or employment
- Receiving a substantial change in income
- Getting married or divorced
- Having children
- Purchasing or selling major assets
- Receiving an inheritance
- Changing retirement expectations
- Experiencing a significant change in financial responsibilities
Even without a major life event, periodic reviews can help identify whether goals, assumptions, and priorities still make sense.
A review does not necessarily mean that everything needs to change. Sometimes the result is simply confirmation that the existing strategy remains appropriate.
Bringing Everything Into One Plan
The value of financial planning often comes from understanding how different decisions affect one another.
A career decision can influence income. Income can affect savings capacity. Savings can affect retirement options. Business ownership can affect both cash flow and estate planning. Family changes can affect insurance, spending, and wealth-transfer objectives.
Looking at these areas separately can make it harder to see those relationships.
A long-term wealth planning strategy can instead bring the different pieces into a broader framework, helping professionals evaluate decisions in the context of their overall objectives. a long-term wealth planning strategy
This does not mean trying to predict every change that will happen over the next several decades. A useful financial plan should leave room for uncertainty.
The goal is to establish a framework that can be reviewed, adjusted, and refined as circumstances evolve.
A Plan Should Evolve With Your Life
Careers change. Families grow. Businesses develop. Income rises and falls. Retirement expectations shift. Priorities that once seemed essential may become less important, while new goals emerge.
Financial planning works best when it reflects those realities.
Instead of treating a financial plan as a fixed document, professionals can view it as an ongoing framework for connecting current decisions with longer-term goals. Regular reviews can help ensure that investments, retirement planning, tax considerations, estate objectives, and changing personal priorities continue to fit together.
The future cannot be planned with complete certainty, but a flexible financial plan can make it easier to respond thoughtfully when life takes an unexpected direction.